When an Alberta property owner receives a formal Notice of Intention to Enforce Security, immediate financial intervention is required. This document serves as a severe statutory warning that a secured creditor is preparing to realize upon their security—meaning they are initiating the legal process to seize and sell the property to recover an outstanding debt. In the 2026 financial landscape, leveraging secondary home equity is one of the most effective methods to immediately cure mortgage arrears, satisfy the demanding creditor, and halt the progression toward a formal Statement of Claim.
Key Takeaways
- Statutory Deadlines: A Notice of Intention to Enforce Security dictates a strict legal timeline, requiring immediate action to prevent the filing of a Statement of Claim.
- Equity Utilization: Borrowers can utilize secondary financing to extract equity, cure the primary mortgage default, and pay accrued legal fees.
- LTV Restrictions: In 2026, alternative lenders typically cap total Loan-to-Value (LTV) at 65% to 75% for properties in active default.
- Recourse vs. Non-Recourse: Understanding Alberta’s Law of Property Act is crucial, as it dictates whether a lender can pursue you for a post-foreclosure financial shortfall.
- Legal Intervention: Securing secondary financing before the expiration of the notice period avoids escalating court costs and Master in Chambers hearings.
Understanding the Notice of Intention to Enforce Security in Alberta
The legal framework governing secured creditors in Canada is rigorous. Under the federal guidelines established by Justice Canada, specifically referencing instruments like the Bankruptcy and Insolvency Act (BIA) and provincial property laws, a Notice of Intention to Enforce Security is a mandatory prerequisite in specific lending scenarios before a creditor can take possession of collateral. While standard residential foreclosures often begin with a formal demand letter, commercial properties, agricultural lands, and cross-collateralized assets frequently trigger statutory notices of intention.
It is crucial to understand the legal distinction by comparing standard demand letters with formal notices. A demand letter is a contractual request for payment, whereas a Notice of Intention is a legally binding statutory document that starts a definitive countdown. Once this timeframe expires, the lender is legally authorized to file a Statement of Claim at the Court of King’s Bench, transitioning the dispute into active litigation.
The Financial Mechanics of Curing Arrears Through Secondary Equity
According to the Canadian Bankers Association, formal enforcement is historically treated as a last resort by primary financial institutions. Lenders prefer that borrowers cure the default. When liquid cash is unavailable, homeowners with sufficient equity can turn to alternative financing to satisfy the demanding creditor.
Secondary financing essentially involves registering a subordinate charge against the property’s title. The funds generated from this new loan are directed immediately to the primary mortgage holder to clear all arrears, penalties, and accrued legal fees, thereby reinstating the original mortgage back into good standing.
Strategy 1: The Arrears Capitalization Approach
The most common strategy is calculating the exact amount required to bring the primary mortgage current, plus an estimation of the next three to six months of payments (an interest reserve). This capital is borrowed through a subordinate lender. By paying the arrears in a lump sum, the Notice of Intention is effectively nullified, as the legal grounds for enforcement—the default—has been cured.
Strategy 2: Total Debt Consolidation and Refinancing
In cases where the primary lender refuses to reinstate the mortgage—which can occur if the borrower has a history of chronic defaults—the secondary strategy shifts from curing arrears to complete property refinancing. This requires finding an alternative or private lender willing to pay out the entire primary mortgage balance. This strategy is heavily dependent on meeting strict appraisal protocols and valuation requirements.
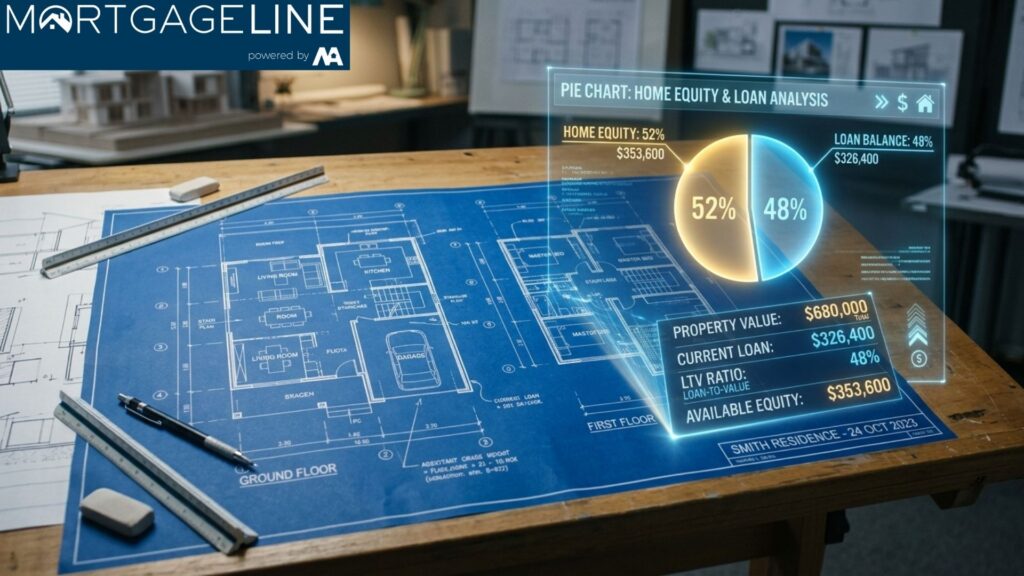
Evaluating Your Property’s Loan-to-Value (LTV) Ratio in 2026
Securing subordinate financing while under the threat of enforcement requires substantial home equity. Data from the Canada Mortgage and Housing Corporation (CMHC) dictates that conventional, federally regulated institutions cannot lend beyond an 80% Loan-to-Value (LTV) ratio on refinances. However, traditional banks will typically automatically decline applications from borrowers currently in default.
Consequently, borrowers must turn to the private lending sector. In 2026, private lenders assessing properties facing enforcement notices generally restrict maximum LTV to between 65% and 75%. The formula is straightforward:
- Determine Current Market Value: Obtain an “as-is” professional appraisal.
- Calculate Maximum Borrowing Capacity: Multiply the appraised value by 0.75 (75%).
- Deduct Existing Encumbrances: Subtract the outstanding balance of the first mortgage, existing property tax arrears, and any registered liens.
- Identify Available Equity: The remaining figure represents the gross funds available to cure the default and cover new lending fees.
| Financial Variable | Conventional Refinance | Private Secondary Financing (Distressed) |
|---|---|---|
| Maximum LTV | Up to 80% | 65% – 75% |
| Income Verification | Strict (T4, NOA, GDS/TDS ratios) | Flexible (Asset-based lending focus) |
| Credit Score Requirement | Typically 680+ | No strict minimum; equity driven |
| Funding Speed | 30 – 60 days | 7 – 14 days |
The Role of Alberta’s Law of Property Act
A unique and highly critical component of Alberta’s real estate legislation is the distinction between recourse and non-recourse mortgages under the Law of Property Act. If an equity strategy fails and the property is seized, this Act determines whether the borrower can be sued for a financial shortfall.
Under Section 40 of the Act, conventional mortgages (where the borrower put down 20% or more at purchase and did not require CMHC insurance) are generally non-recourse. This means if the lender forces a sale and the property sells for less than the outstanding debt, the lender cannot pursue the borrower personally for the difference. Conversely, high-ratio insured mortgages are recourse loans, leaving the borrower fully liable for any deficiency judgment.
Understanding this legal distinction is vital when weighing whether to fight the enforcement by taking on higher-interest secondary debt, or to negotiate a surrender of the property. For some homeowners, signing a quit claim deed might be a strategic alternative to accumulating more debt if the property lacks sufficient equity to support a financial rescue.
Clearing Encumbrances to Facilitate New Financing
Before a subordinate lender will register a new charge against the title, the title must be analyzed for existing encumbrances that could threaten their security position. The most prominent threat is unpaid municipal taxes. Under Alberta law, municipal property taxes form a super-priority lien, meaning they rank ahead of all mortgages, regardless of when the mortgages were registered.
If the borrower has ignored their tax obligations, the secondary financing must be sized large enough to immediately clear these debts. It is a mandatory condition of funding that the legal representative use the loan proceeds to clear municipal tax arrears prior to releasing the remaining funds to the primary mortgage lender.
Navigating the Litigation Phase: Court of King’s Bench
If the statutory notice period expires before the homeowner can secure alternative funding, the lender will file a Statement of Claim. Once served, the borrower has 20 days (if served in Alberta) to file a Statement of Defence or a Demand for Notice. Failing to respond results in the borrower being “Noted in Default,” severely limiting their ability to participate in the court process.
At this juncture, any secondary financing strategy becomes inherently more complex and expensive. The primary lender’s legal costs are added to the redemption amount, escalating the total debt. The borrower will eventually face Master in Chambers proceedings, where the court reviews the case and issues an Order Nisi.
The Order Nisi establishes the Redemption Period—a court-ordered timeframe (typically six months, though it can be reduced to one day if the property has negative equity) during which the borrower has the absolute right to pay off the debt. A skilled legal team, backed by an approved secondary mortgage commitment, can often successfully petition the court for extending the redemption period to allow the complicated refinancing transaction to close.
Mitigating Legal Risks and Alternative Resolutions
When assessing equity extraction to combat a Notice of Intention, borrowers must calculate the exit strategy. A one-year private mortgage acts as a financial bridge, not a permanent solution. The borrower must have a verifiable plan to transition back to a conventional lender within 12 to 24 months, which usually involves improving their credit score, stabilizing their income, or preparing the property for an orderly sale.
If secondary financing is deemed unviable due to insufficient LTV or inability to service the new interest payments, litigation mitigation is the next step. Borrowers can work with their legal counsel on negotiating a consent order, allowing them to remain in the home for an agreed-upon period while listing the property for sale voluntarily, thereby avoiding the stigma and aggressive legal costs of a forced judicial sale.
Economic Context: Alberta’s 2026 Real Estate Climate
The macroeconomic environment of 2026 heavily influences a lender’s willingness to advance equity loans during active enforcement. Data aggregated from Statistics Canada highlights that regional property values and employment stability play pivotal roles in private lending algorithms. In regions where property values are robust, lenders are significantly more willing to provide capital to cure defaults, knowing the collateral provides adequate security.
Borrowers must proactively present their property in the best possible light. Ensuring the property is well-maintained and providing up-to-date property tax certificates and first mortgage statements can expedite the underwriting process, which is critical when the statutory clock of a Notice of Intention is ticking.
Frequently Asked Questions (FAQ)
What is a Notice of Intention to Enforce Security in Alberta?
It is a formal statutory document served by a secured creditor indicating their legal intent to realize upon their collateral due to a default. It initiates a strict countdown before the lender can escalate to filing a Statement of Claim in court.
Can a second mortgage stop a foreclosure in its tracks?
Yes, if the funds from the secondary financing are used to pay all mortgage arrears, penalties, and accrued legal costs in full, the default is legally cured. This forces the primary lender to reinstate the mortgage and halt all enforcement proceedings.
What credit score is required to get a distressed equity loan?
Private lenders focusing on enforcement rescues base their underwriting almost entirely on property equity rather than the borrower’s credit score. As long as there is sufficient equity (typically 25% to 35% remaining after all debts), credit scores are largely secondary.
Will the new lender pay my property tax arrears?
Yes, any new lender will mandate that outstanding municipal property taxes are paid directly from the loan proceeds. This is because property taxes form a super-priority lien that ranks ahead of all registered mortgages in Alberta.
What happens if I cannot secure secondary financing in time?
If the deadline expires without the default being cured, the primary lender will proceed to court to obtain an Order Nisi. You will then have a court-determined redemption period to either pay the debt, sell the property, or face a judicial sale or foreclosure order.
Conclusion
Receiving a Notice of Intention to Enforce Security is a critical legal event that demands immediate, calculated action. Ignoring this statutory warning will inevitably lead to a Statement of Claim, escalating legal costs, and the eventual loss of the property. In 2026, leveraging secondary financing remains one of the most powerful and expedient strategies to cure arrears, satisfy the primary lender, and protect your accumulated equity. Success depends entirely on acting swiftly within the notice period, securing accurate property valuations, and partnering with experienced legal and financial professionals to orchestrate the payout. If you are facing enforcement and need to explore your equity options, time is of the essence. Contact our team today to review your situation and implement a strategy to protect your home.