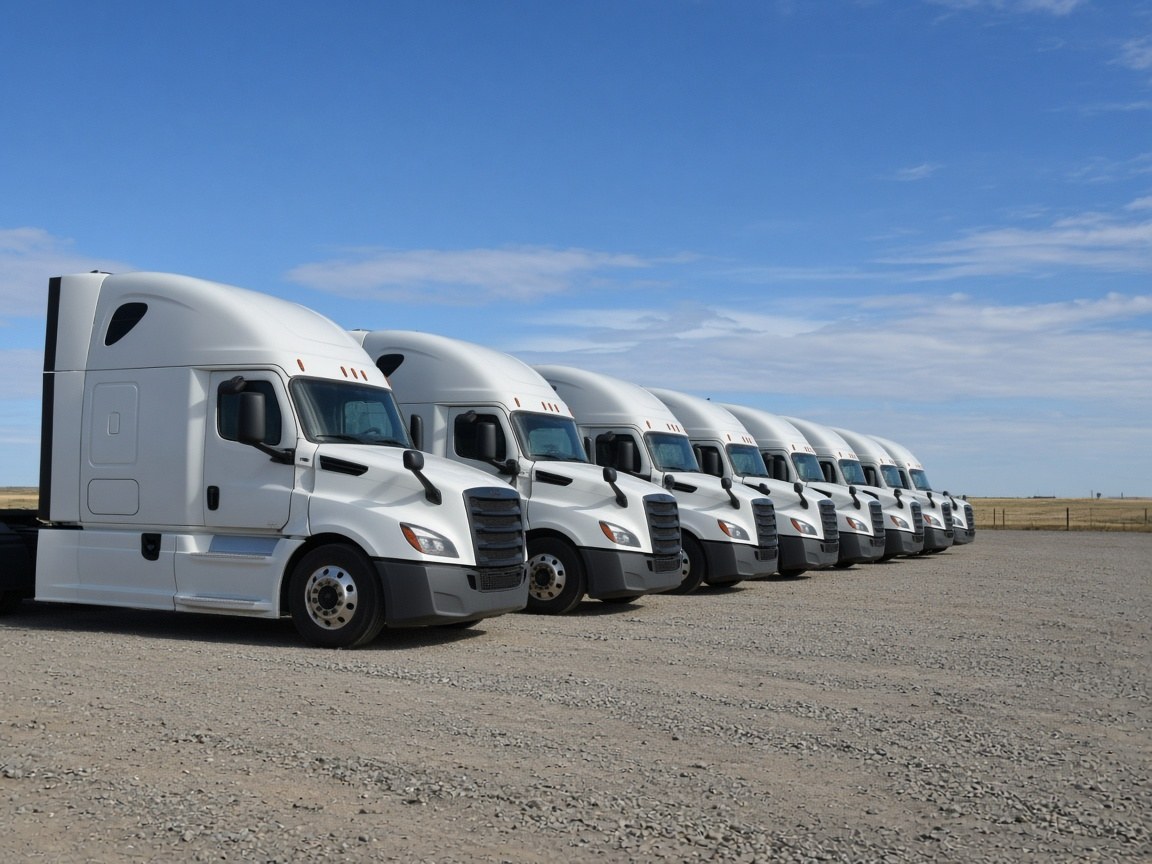
Yes, a second mortgage can help a Calgary trucking owner expand a fleet if the home has enough equity. The money is borrowed against your house. It can pay for a down payment, a used unit or start-up costs. It is not the cheapest route, and it puts your home behind the business, so a clear plan matters.
Owner-operators and small carriers often grow a truck at a time. A new contract comes in, and the business needs another unit on the road. Truck lenders may want a large down payment or a longer track record first.
At The Second Mortgage Store, Lance Dawson has spent 22+ years helping Calgary homeowners use equity carefully. We look at the contract, the truck deal and your home. Then we tell you plainly whether a second mortgage fits.
This guide explains where home equity fits in a fleet plan. It covers down payments, carrier requirements, seasonal income and the risks of tying your house to the road.
Table of Contents
- Fleet Expansion and Home Equity at a Glance
- Where Home Equity Fits Beside Truck Financing
- Carrier Requirements That Come With More Trucks
- Seasonal Loads and Uneven Income
- What Lenders Look at for an Owner-Operator
- Running the Numbers Before You Add a Unit
- Frequently Asked Questions
- Talk to a Calgary Broker About Growing Your Fleet
Fleet Expansion and Home Equity at a Glance
A second mortgage is a new loan registered behind your first mortgage. Your first mortgage stays in place. The lender sizes the new loan to the equity left in your home.
For a trucking owner, that money is flexible. It can cover a down payment, a used truck or trailer, licensing costs or working capital while a new unit ramps up. The lender looks mainly at your home and your ability to carry both payments.
Truck financing works differently, because the truck usually secures the loan. Home equity can sit beside that financing or fill a gap it leaves. Either way, the house becomes part of the fleet plan. That is the trade-off to weigh before you sign.
Got a new contract and need another unit on the road? Send us the truck deal and your first-mortgage statement. We will tell you what your equity could support.
Where Home Equity Fits Beside Truck Financing
Most owners start with a truck dealer or an equipment lender. Those lenders finance the unit and hold it as security. They often ask for a down payment and a history of steady work.
Home equity can help where that route falls short. Some owners use a second to cover the down payment so the truck loan is smaller. Others use it to buy a used unit outright when a lender will not finance an older truck.
There is a cost to that flexibility. A second mortgage, especially from a private lender, usually costs more than a first mortgage. Fees add up on a short term, so compare the full cost before you choose.
Keep the borrowing tight and focused. Fund the unit and the start-up costs, not a wish list. The smaller the second, the easier it is to pay off when the new truck starts earning.
Ask about prepayment terms as well. If a strong season lets you clear the loan early, you want that option. Some lenders charge for early repayment, so get the terms in writing.
Carrier Requirements That Come With More Trucks
More trucks can mean more paperwork. In Alberta, a carrier is the owner of commercial vehicles such as large trucks or trailers. The province explains its Safety Fitness Certificate rules for commercial carriers on its carrier certificate page.
That page lists what carriers need when they renew a certificate. It includes insurance coverage, operating status, the nature of the business and the people in charge of safety and maintenance. Whether a certificate applies depends on vehicle weight and where you operate.
Changing how you operate can change your requirements. For example, moving from work inside Alberta to hauling outside the province may bring different rules. Check with the province before you take on new routes.
Budget for these costs in your plan. Insurance for an added unit, plates, inspections and safety program work all cost money. A lender will be more comfortable when your plan shows you have counted them.
We are a mortgage brokerage, not a safety consultant or a law firm. Confirm your carrier obligations with the province or a qualified advisor. We focus on the financing side once the plan is clear.
Seasonal Loads and Uneven Income
Trucking income rarely arrives in a straight line. Some months are full, and others are thin. Fuel, repairs and slow-paying customers can squeeze cash flow at the wrong time.
That pattern matters to a lender. Bank lenders usually want steady, documented income. Owner-operators with large write-offs may show less income on paper than they actually earn.
Private lenders lean more on equity and the exit plan than on income. They may look at a file a bank would decline. Expect the rate and fees to reflect that flexibility.
Plan the payments around your slowest months, not your best ones. If a new truck sits idle for a few weeks, both mortgage payments still come due. A cash reserve can carry you through a slow stretch.
Slow-paying customers deserve a line in the plan too. A load delivered today may not be paid for weeks. Ask your accountant how long your receivables usually take to come in.
Wondering how a lender will read your trucking income? Lance Dawson brings 22+ years of experience to self-employed files. We will review your documents before anyone orders an appraisal.
What Lenders Look at for an Owner-Operator
The home comes first. Expect a lender to ask for your land title, first-mortgage statement and a recent property tax notice. An appraisal will confirm the value.
Next comes income, which is often the harder part for trucking owners. Bring your recent tax returns, business bank statements and any signed contracts. A contract that shows steady work for the new unit can help your case.
Credit history matters too, for bank and private lenders alike. Late payments on equipment or fuel cards can push a file toward private lenders. Pull your credit report early so nothing catches you off guard.
Explain the plan in a few short sentences, in plain language. Say what the new truck will haul, who it will haul for and how the second gets repaid. Lenders respond well to owners who know their numbers.
If your business is incorporated, say so early. The home is usually in your personal name, while the trucks may sit in the company. Your accountant can explain how the funds should move between them.
Running the Numbers Before You Add a Unit
An added truck has to cover more than its own loan. Fuel, insurance, maintenance, tires and a driver’s pay all come first. What is left has to cover your share of the second mortgage.
Work through a realistic month with your accountant. Use honest rates for fuel and repairs, not best-case guesses. Include downtime for maintenance and slow weeks between loads.
If the numbers only work in a perfect month, wait. A smaller loan, a used unit or a longer contract may make the plan safer. There is no shame in growing more slowly.
Compare the added unit with other options too. Leasing a truck, subcontracting loads or adding a lease operator may cost less upfront. Home equity makes the most sense when buying clearly beats those choices.
Think about the exit too. Private seconds often run on short terms. You might refinance once the business has a stronger track record, pay down the loan from profits or sell the unit.
Talk with anyone else on your home’s title before you apply. A spouse or co-owner will need to sign, and the house is their home too. Agreement at home matters as much as the business plan.
Frequently Asked Questions
Can a trucking company owner get a home equity loan?
Yes, if the home has enough equity and you can carry the payments. The loan is registered against the home, usually in your personal name. Talk to your accountant about how the business uses the funds.
What disqualifies you from a second mortgage as an owner-operator?
Thin equity is the most common barrier. Very weak income records or unresolved credit problems can also stop a bank lender. Private lenders may still help, at a higher cost.
Is a second mortgage cheaper than truck financing?
Not usually, because truck lenders hold the unit as security. A second may cost more but can fill a gap truck financing leaves. Compare the full cost of each before you decide.
How fast can a second mortgage fund a truck purchase?
It depends on the appraisal, the lender and the lawyer’s schedule. Private lenders can often move faster than banks. Having your documents ready saves the most time.
Talk to a Calgary Broker About Growing Your Fleet
A second mortgage can help a Calgary trucking owner add a unit when other financing falls short. Count every cost, plan for slow months and keep the borrowing tight. Then compare full costs in writing.
The cost of a second is more than its rate. Ask for the lender fee, brokerage fee, legal and appraisal costs up front. A low rate with a large fee can cost more on a short term.
See how a private mortgage in Calgary can fund an owner-operator with uneven income for more on private lenders. Lance Dawson (BA adv., MA) brings 22+ years of experience to every file. We cannot guarantee an approval, and we show the full cost before you commit.
If you are ready to add a truck, talk to us first. We will look at your equity and the deal and tell you plainly what fits.