When facing the threat of losing a home in Alberta, homeowners have several legally protected avenues to retain their property, even after a court order has been issued. Stopping a foreclosure when an Order Nisi is active requires immediate action, a clear understanding of provincial real estate law, and access to the necessary capital to satisfy the lender’s demands before the judicial redemption period expires.
Key Takeaways
- An Order Nisi is a conditional court order in Alberta that establishes a specific “redemption period” (usually 6 months) for the homeowner to pay their arrears or the full mortgage balance.
- Homeowners can halt the legal process by redeeming the mortgage, refinancing through alternative lenders, or selling the property independently.
- Applications can be made to a Master in Chambers to request an extension of the redemption period if sufficient home equity exists.
- Failing to act before the deadline typically results in a Final Order for Foreclosure or a Rice Order, transferring the property to the lender.
- Engaging specialized legal representation and exploring alternative equity financing immediately is critical to protecting your real estate assets in 2026.
Understanding the Order Nisi in Alberta Law
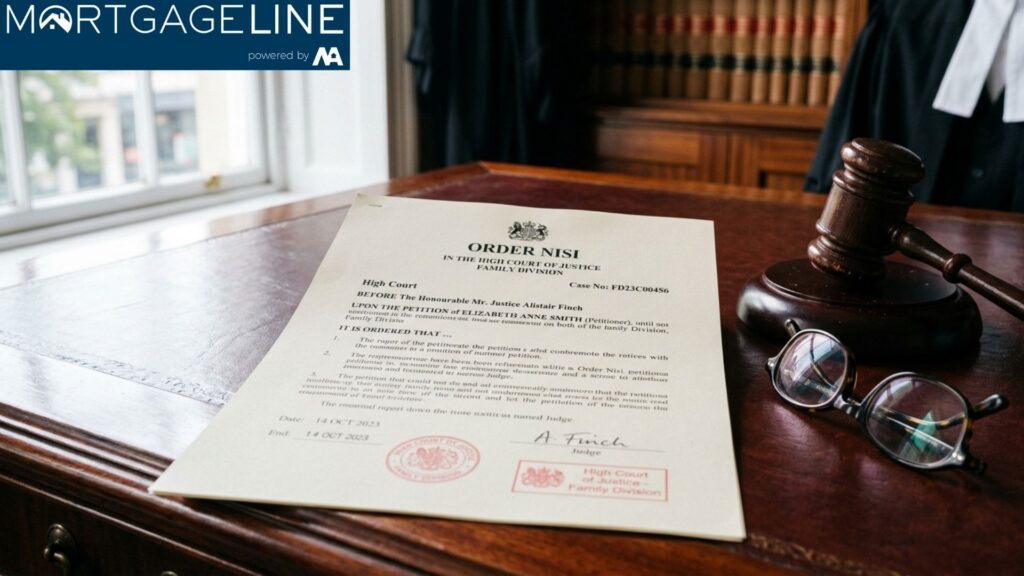
In the Alberta legal system, foreclosure is an action governed heavily by the Law of Property Act. The process begins when a lender files a Statement of Claim following missed mortgage payments. If the homeowner does not file a Statement of Defence, or if the lender’s claim is successful in court, a judicial officer will grant an Order Nisi. This is the most critical juncture in the legal timeline.
An Order Nisi is not a final judgment of loss; rather, it is a conditional order. It officially recognizes the amount owed to the lender and establishes a “redemption period.” During this period, the homeowner retains possession and title of the property and is granted a final opportunity to remedy the default. Historically and legally, the standard redemption period granted in Calgary courts is six months, although a judge can reduce this to as little as one day if the property is abandoned, uninsured, or if there is zero equity remaining in the home.
According to guidelines published by the Law Society of Alberta, homeowners maintain the absolute right to redeem their mortgage during this timeframe. This means the legal action can be fully reversed if the financial conditions of the order are met.
4 Verified Methods for Halting the Action After an Order Nisi
Homeowners in Calgary facing this situation are not without options. The judicial system is designed to prefer that lenders recover their funds rather than seize property. Here are the four primary strategies to resolve the situation.
1. Reinstating or Paying Out the Mortgage
The most direct method to stop the proceedings is to satisfy the financial demands outlined in the court documents. This involves requesting a formal payout statement from the lender’s legal counsel. The statement will detail the principal balance, accumulated interest, property tax arrears (if any), and the associated legal costs.
If the mortgage has not been accelerated, the homeowner may only need to pay the arrears and legal fees to reinstate the loan. If the mortgage has been fully accelerated, the entire principal balance becomes due. Resolving this immediately discharges the court action and restores standard homeownership rights.
2. Securing Alternative Equity Financing
If a homeowner lacks the liquid cash to pay the arrears, alternative financing is often the next step. Traditional A-lenders (major banks) will strictly decline to refinance a property currently under legal action. Therefore, homeowners must seek out private equity financing. Private lenders focus primarily on the remaining equity in the home rather than the borrower’s immediate credit score.
By securing a new loan to clear the existing mortgage or the arrears, the homeowner effectively buys out the foreclosing lender. This is a common and effective method for halting the legal proceedings before the expiration date.
3. Selling the Property Independently
If retaining the property is no longer financially viable, selling it on the open market is vastly preferable to allowing the court to seize it. A traditional market sale almost always yields a higher purchase price than a court-ordered sale. Homeowners can list the property with a licensed real estate agent during the redemption period.
If an offer is accepted, the proceeds of the sale are used to pay off the foreclosing lender, clear the title, and distribute any remaining equity directly to the homeowner. This proactive approach prevents a complete loss of accumulated wealth.
4. Requesting a Redemption Period Extension
In cases where the homeowner is actively trying to sell or refinance but needs more time, they can apply for an extension. This requires formal appearances before a Master in Chambers. To successfully obtain an extension, the homeowner must prove three key elements: there is substantial equity in the property, they are making a genuine effort to sell or refinance, and the lender’s financial position will not be jeopardized by the delay.
Understanding the criteria for extending your redemption timeframe is vital, as courts will not grant more time without documented proof of progress.
The Legal Timeline: Comparing Outcomes
It is crucial to differentiate between the various court orders utilized in Alberta. If the redemption timeframe lapses without resolution, the lender will apply for a subsequent order to take control of the asset.
| Legal Action | Homeowner Status | Equity Status | Outcome |
|---|---|---|---|
| Order Nisi | Retains possession & title | Protected during redemption period | Conditional timeframe granted to resolve debt |
| Final Order for Foreclosure | Title transfers to lender | Forfeited to the lender | Lender takes the property in full satisfaction of the debt |
| Rice Order | Title transfers to lender | Determined by court valuation | Lender purchases property; may pursue borrower for shortfall |
| Order for Sale | Property listed by court | Surplus returned after costs/debt | Judicial sale to a third-party buyer |
In cases where property values have dropped below the mortgage balance, lenders frequently pursue a Rice Order. Conversely, if there is high equity, the court typically mandates judicial sale mechanisms to ensure the homeowner’s remaining equity is protected after the debts are cleared.
Economic Context: 2026 Calgary Real Estate Realities
Navigating property distress requires an understanding of the broader economic environment. In 2026, the Calgary housing market operates under strict federal and provincial monetary conditions. Data from Statistics Canada continuously monitors household debt-to-income ratios, which serve as leading indicators for mortgage defaults.
As Benjamin Tal, Deputy Chief Economist at CIBC, has frequently noted regarding Canadian real estate debt: “Higher interest rates act as a significant stress test for homeowners, making alternative financing and proactive equity management crucial during economic transitions.”
Historically, Alberta has seen mortgage arrears rates fluctuate around 0.45% to 0.60% during periods of economic shifting. When household budgets tighten, the Bank of Canada closely observes these vulnerabilities. As Tiff Macklem, Governor of the Bank of Canada, stated regarding household debt: “While the financial system remains resilient, heavily indebted households face significant pressures during periods of elevated borrowing costs.”
Furthermore, the Canada Mortgage and Housing Corporation (CMHC) provides ongoing analysis of housing market risks, emphasizing that early intervention is the most effective way to preserve homeowner equity.
Step-by-Step Action Plan for Calgary Homeowners
If you have been served with court documents and a conditional order for sale is currently active, follow this structured action plan:
- Review the Court Documents: Immediately identify the precise date the redemption period expires. This date dictates your timeline for all subsequent actions.
- Consult a Specialized Lawyer: Retain legal counsel experienced in Alberta property law. They can communicate directly with the lender’s lawyers and ensure no procedural rights are violated.
- Determine the Accurate Payout Figure: Have your lawyer request an official payout statement. Legal fees can escalate rapidly, sometimes adding $3,000 to $10,000 to the total debt if the action is prolonged.
- Assess Property Value: Obtain a professional appraisal. The court relies heavily on these valuations. Understanding the strict appraisal requirements ensures you know exactly how much equity you have to work with.
- Apply for Financing or List the Property: Engage a private mortgage broker to secure an equity loan, or immediately list the home on the MLS with an aggressive pricing strategy to secure a buyer before the deadline.
The Importance of Acting Early
Delaying action is the most common mistake made during real estate litigation. As Phil Soper, President and CEO of Royal LePage, has accurately summarized regarding market dynamics: “The resilience of the housing market depends heavily on how homeowners navigate periods of financial strain, particularly in regions tied to cyclical industries.”
Once the redemption timeframe expires, reversing the process becomes exponentially more difficult and expensive. The courts view the expiration of the Order Nisi as a failure to remedy the breach of contract. By taking immediate, proactive steps—whether through refinancing, selling, or negotiating—homeowners retain control over their financial future and prevent the total loss of their property investments.
Conclusion
Stopping a foreclosure when an Order Nisi is active in Calgary is entirely possible, provided homeowners act decisively within the court-mandated redemption period. By understanding the legal mechanisms under the Alberta Law of Property Act, leveraging remaining home equity, and securing proper legal and financial counsel, you can successfully halt the proceedings. Whether you choose to refinance, sell, or seek a judicial extension, prioritizing immediate action protects your most valuable asset from seizure.
If you are facing an active court order and need immediate assistance exploring alternative financing options to save your home, contact our team today for a confidential consultation.
Frequently Asked Questions (FAQ)
Can I still live in my house after an Order Nisi is granted?
Yes. You maintain full possession, occupancy, and legal title of the property throughout the entire redemption period specified in the court order.
How long is the standard redemption period in Calgary?
In standard cases under Alberta law, the court grants a six-month redemption period. However, this can be significantly shortened if the property is vacant or lacks equity.
Will a consumer proposal automatically stop the foreclosure?
A consumer proposal provides a temporary “stay of proceedings,” but because a mortgage is a secured debt, the lender can eventually apply to lift the stay and continue the action.
Can I sell my home privately during this legal process?
Absolutely. You have the legal right to list and sell the property on the open market before the redemption period expires, which is often the best way to preserve your equity.
What happens if I ignore the Order Nisi?
If the deadline passes without the debt being satisfied, the lender will return to court to seek a Final Order for Foreclosure or a Rice Order, resulting in the complete loss of the property.
Do I still have to pay property taxes and insurance during this time?
Yes. Failing to maintain home insurance or pay municipal property taxes can be used by the lender as grounds to apply to the court to shorten your redemption period.